Private sector NFPs: Introduction to simplified general purpose financial statements for Tier 3 entities
Why was AASB 1061 developed?
AASB 1061 was developed to provide a simpler solution for smaller NFPs currently preparing special purpose financial statements that will have to prepare general purpose financial statements (GPFS) beyond 2029.
Which entities can apply AASB 1061?
Not all NFPs can apply AASB 1061. However, entities eligible to apply Tier 3 may choose to prepare Tier 1 or Tier 2 general purpose financial statements (GPFS).
Which entities can report under the new Tier 3 standard?
AASB 1053 provides that entities that can apply Tier 3 are NFP private sector entities that:
- Do not have public accountability, and
- Are not prohibited by legislation, their constituting document or another document from applying AASB 1061.
Examples of entities that AASB 1061 may apply to include charities, companies limited by guarantee, incorporated associations and co-operatives. However, the AASB decided not to specify which types of entities could prepare Tier 3 GPFS and noted that it is more appropriate for the relevant legislation or regulatory authority to set size thresholds or other criteria, as appropriate.
Currently, charities registered with the ACNC may prepare SPFS under section 60.30 of the Australian Charities and Not-for-profits Commission Regulations 2022. This also applies to companies limited by guarantee that are not registered with the ACNC and preparing financial statements under Chapter 2M of the Corporations Act 2001. In both cases, the SPFS must comply with, as a minimum, AASB 101 Presentation of Financial Statements, AASB 107 Statement of Cash Flows, AASB 108 Accounting Policies, Changes in Accounting Estimates and Errors, AASB 1048 Interpretations of Standards, and AASB 1054 Australian Additional Disclosures. In addition, ACNC-registered entities must also disclose related party information (AASB 124 Related Party Disclosures).
We expect regulators to provide more information regarding Tier 3 thresholds or qualifying criteria in due course.
Is AASB 1061 a ‘one-stop shop’?
Generally, AASB 1061 contains all the recognition, measurement, presentation and disclosure requirements for Tier 3 entities preparing GPFS. However, if applicable, Tier 3 entities will have to refer to the recording, measurement and presentation requirements in:
- AASB 2 Share-based Payment, in relation to share-based payment arrangements
- AASB 5 Non-current Assets Held for Sale and Discontinued Operations, in relation to non-current assets held for sale except for:
- Financial assets within the scope of Section 10 of AASB 1061, and
- Investment properties measured using the fair value model in Section 14 of AASB 1061
- AASB 6 Exploration for and Evaluation of Mineral Resources, in relation to exploration for, and evaluation of, mineral resources
- AASB 9 Financial Instruments and other applicable Australian Accounting Standards, in relation to ‘non-basic’ financial instruments
- AASB 17 Insurance Contracts, in relation to insurance contracts issued by the entity
- AASB 119 Employee Benefits, in relation to obligations arising under a defined benefit plan
- AASB 141 Agriculture, in relation to biological assets (except for bearer plants, and agricultural produce at the point of harvest).
For these topics, Tier 3 entities must refer to the relevant disclosures required by AASB 1060 General Purpose Financial Statements – Simplified Disclosures for For-Profit and Not-for-Profit Tier 2 Entities.
Are all the requirements in AASB 1061 simplified?
No. AASB 1061 generally uses simplified drafting language, has simplified presentation requirements and fewer disclosures overall compared to Australian Accounting Standards, including AASB 1060.
However, simplified recording and measurement mainly applies to items such as non-financial assets acquired for significantly less than fair value, internally generated intangible assets, leases, employee benefits, revenue, consolidation, entity combinations, basic financial instruments, impairment losses, income taxes and changes in accounting policies. Recording and measurement of most other items remain the same or similar, using simplified language appropriate for Tier 3 entities.
AASB 1061 also contains new disclosures in some cases where the recording and measurement requirements are simpler than those in Tier 2 (AASB 1060).
When does AASB 1061 apply?
AASB 1061 applies to annual reporting periods beginning on or after 1 July 2029 and can be adopted early.
Despite the early adoption option, until legislators clarify which entities can use it, we recommend that private sector NFPs consider carefully and seek advice regarding adopting AASB 1061 before 1 July 2029.
Transition options
When first applying AASB 1061, the ‘date of transition’ is the beginning of the current period. Entities can choose to apply one of the following transition options:
- Option 1: Apply the specific transition requirements in paragraphs 28.8 to 28.12 of AASB 1061, which include targeted reliefs and exemptions and reduce the complexity of first-time adoption, or
- Option 2: Retrospectively apply the recording and measurement requirements of AASB 1061 as if the entity had always applied the Tier 3 reporting requirements. This is a modified retrospective approach, with transition adjustments recognised on the transition date, and no restatement of comparatives in either the statement of financial performance or position.
For Option 1, an entity can choose to restate comparatives in its first AASB 1061 GPFS. In this case, the ‘date of transition’ is the beginning of the earliest comparative period presented.
For Option 2:
- The entity does not have to correct prior period errors retrospectively but can instead adjust the cumulative effect on the transition date, and
- Comparative information for narrative disclosures in the notes is not required if the entity did not disclose that information in its most recent previous financial statements.
Financial statement presentation (section 2)
This section covers fair presentation, compliance with AASB 1061, going concern, frequency of reporting, consistency of presentation, comparative information, materiality and aggregation, offsetting, what makes up a complete set of financial statements, and identification of the financial statements. These presentation and disclosure requirements are broadly consistent with the equivalent Tier 2 requirements in AASB 1060. However, we note the following differences:
- Going concern
There is additional guidance that management judgement is required to determine whether the carrying amounts of assets and liabilities need to be adjusted. This will depend on whether the entity intends to transfer operations to another entity, have an orderly sale of operations or assets, or whether there will be a forced or rushed liquidation of assets.
The entity also needs to consider whether changes in circumstances may lead to additional liabilities or trigger clauses in debt covenants, resulting in the reclassification of debts as current liabilities.
- Consistency of presentation
No detailed disclosure is required regarding the reclassification of items in prior periods, i.e., the nature, amount and reason.
- Complete set of financial statements
The statement of profit or loss and other comprehensive income is referred to as the ‘statement of financial performance’.
- Presentation currency
Tier 3 financial statements must be presented in Australian dollars (AASB 1060 permits a presentation currency other than Australian dollars).
Statement of financial position (section 3)
The presentation and disclosure requirements regarding the statement of financial position are broadly similar to Tier 2, except we note that:
- For detailed line items - biological assets and non-current assets held for sale are not required because Tier 3 entities must refer to the Tier 2 requirements when accounting for these items
- Deferred tax assets and liabilities are not required because they are not recognised under AASB 1061
- The liquidity presentation format is not permitted for Tier 3, and entities will have to present current and non-current assets and liabilities in the statement of financial position (the assumption that the normal operating cycle is assumed to be twelve months has been removed from the current/non-current classification requirements for assets)
- Entities with share capital don’t have to provide additional information regarding shares, rights, preferences and reconciliations, which makes sense as many NFP private sector entities may not have ordinary corporate share capital structures.
Statement of financial performance (section 4)
The presentation and disclosure requirements regarding the statement of financial performance are consistent with Tier 2, except we note that:
- Profit or loss from discontinued operations is omitted because Tier 3 entities must refer to the Tier 2 requirements when accounting for these items
- Items of other comprehensive income do not have to distinguish whether or not they will be reclassified subsequently to profit or loss
- References to profit or loss or other comprehensive income of associates and joint ventures accounted for using the equity method have been expanded to include notable relationships accounted for in the same way
- Expenses can be classified by nature, by function, or by using a mixed presentation, provided that it represents the most useful, structured summary of expenses.
In addition, changing from a single statement of profit or loss and other comprehensive income to two statements is not considered a change in accounting policy.
Statement of changes in equity (section 5)
The requirements here are also mainly consistent with AASB 1060, except:
- The reconciliation for each component of equity only requires separate disclosure of contributions by owners in their capacity as owners, and changes of ownership interests in subsidiaries that do not result in a loss of control. Distributions to owners don’t have to be disclosed, as these are not expected to be common for NFP private sector entities
- The statement of income and retained earnings is not permitted if there are distributions to owners during the period
- A change between presenting a statement of income and retained earnings to presenting a statement of financial performance and a statement of changes in equity (and vice versa) is not a change in accounting policy.
Statement of cash flows (section 6)
The requirements for the statement of cash flows are essentially the same across Tier 2 and Tier 3. However, for Tier 3:
- Only cash flows from operating activities must be shown separately. Cash flows from investing and financing activities can be shown separately or as a combined section for ‘other activities’.
- Examples of cash flows from operating activities include NFP-specific examples, such as grants and donations received and paid to beneficiaries.
- The detailed requirements in AASB 1060 regarding presenting the unrealised gain or loss on remeasuring foreign currency bank accounts separately from cash flows from operating and other activities has been removed (although in practice, in order to ‘balance’ the cash flow statement, the unrealised gain or loss from translating foreign currency cash balances at the year-end exchange rate would need to be shown in the cash flow statement, separately from operating and other activities).
- A reconciliation of the cash and cash equivalent amounts presented in the statement of cash flows to the equivalent items presented in the statement of financial position is not required, even if the amounts are different.
- No disclosure is required for supplier finance arrangements.
Notes to the financial statements (section 7)
These are also consistent across both tiers of reporting, but disclosure of imputation credits has been removed (mainly because NFPs are not expected to declare franked dividends).
Consolidated and separate financial statements (section 8)
Except in limited circumstances, a parent entity preparing Tier 2 financial statements under AASB 1060 General Purpose Financial Statements – Simplified Disclosures for For-Profit and Not-for-Profit Tier 2 Entities must present consolidated financial statements if it has investments in subsidiaries. Despite the additional implementation guidance in Appendix E, consolidation is often one of the most challenging aspects for preparers of NFP financial statements. Indeed, the requirement to present consolidated financial statements was often the reason many NFPs have, to date, prepared special purpose financial statements.
AASB 1061 simplifies the consolidation requirements for Tier 3 NFP entities by providing a choice to either present consolidated financial statements or separate financial statements (with no consolidation).
When must a Tier 3 NFP prepare consolidated financial statements?
A parent entity (investor) must present consolidated financial statements if it controls another entity (investee). It may also choose to present separate financial statements, in addition to the consolidated financial statements (paragraph 8.2).
Consolidated financial statements must include all subsidiaries of the parent entity and must equity account all investments in associates and joint ventures.
The consolidation procedures in AASB 1061 are broadly consistent with the Tier 2 consolidation requirements contained in AASB 10. However, there may be some differences, for example:
- AASB 1061, paragraphs 8.23 and 8.24, do not specify what happens to accumulated other comprehensive income (OCI) relating to a former subsidiary when control is lost
- AASB 10, paragraph B98(c) and B99 require amounts previously recognised in OCI to be reclassified to profit or loss or transferred directly to retained earnings, following the treatment that would apply on disposal of the underlying asset or liability.
Can parent entities choose not to present consolidated financial statements?
Yes, they can. Although paragraph 8.2 says that a parent entity ‘shall’ (must) present consolidated financial statements, paragraph 8.3 then permits an investor to choose not to present consolidated financial statements.
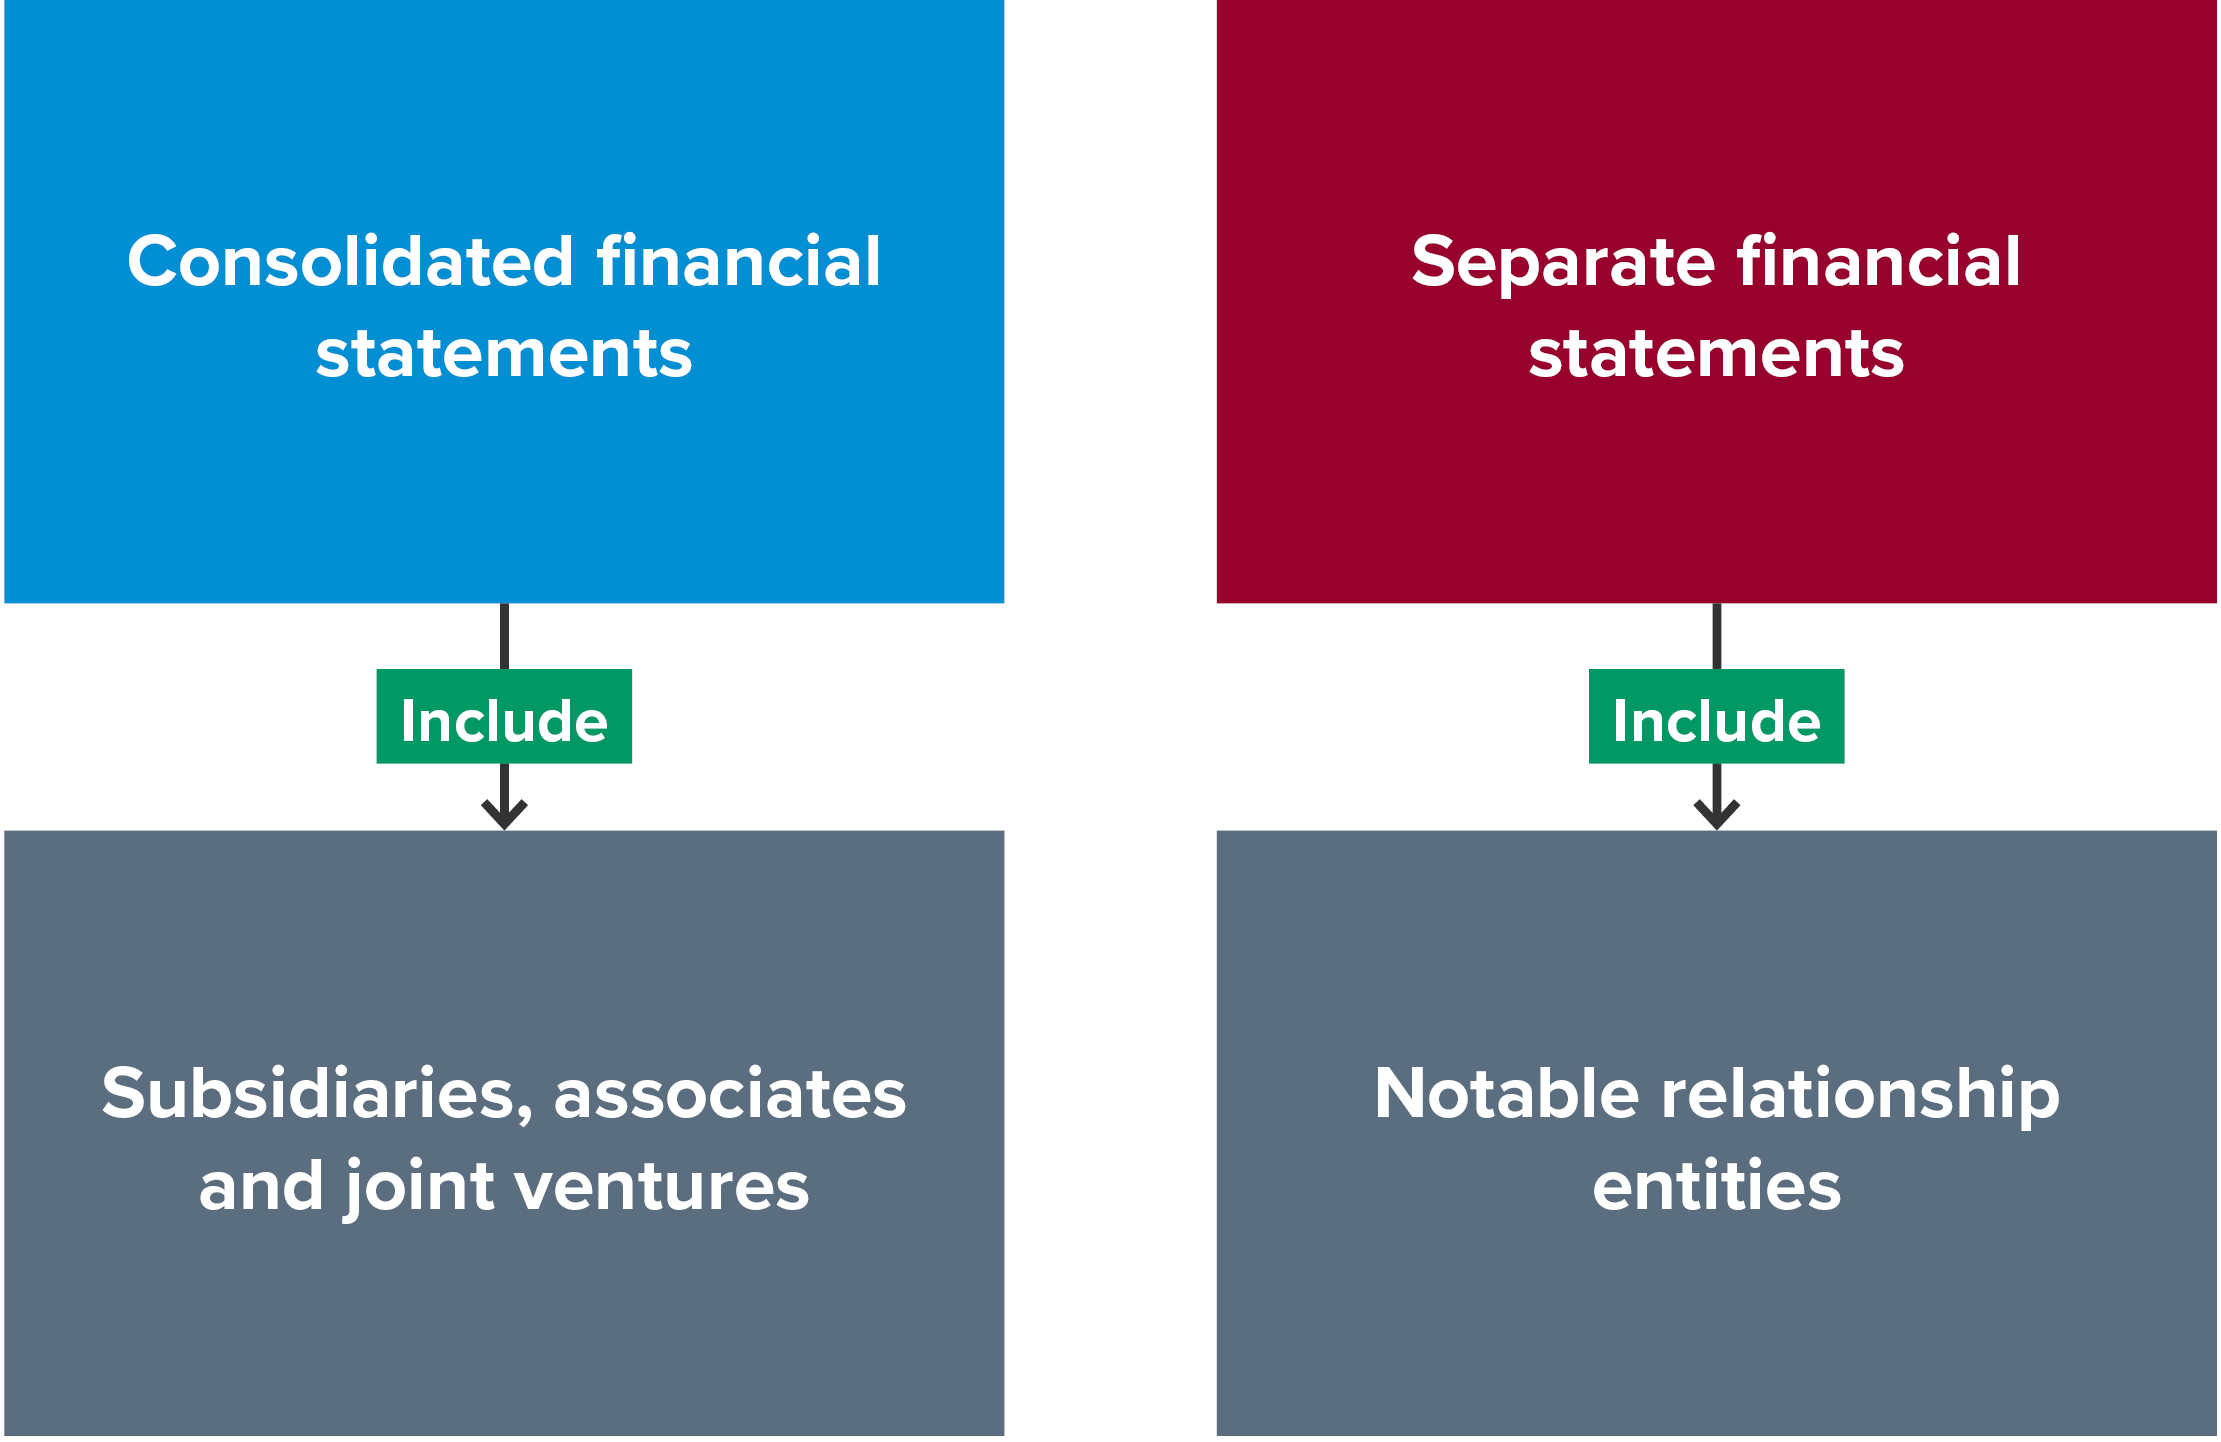
If the investor chooses not to present consolidated financial statements, it collectively classifies all the following types of investments as a single class of assets called ‘investments in notable relationship entities’:
- Subsidiaries
- Associates
- Interests in joint arrangements that involve a separate vehicle (a joint venture).
In such cases, the parent entity prepares separate financial statements as its only financial statements.
An arrangement over which the entity has joint control, but that is not structured through a separate vehicle (e.g. some joint operations), is never a notable relationship entity. Instead, such arrangements are accounted for in accordance with Section 13: Investments in Associates and Interests in Joint Arrangements, of AASB 1061.
Where consolidated financial statements are not prepared, AASB 1061 requires an entity to treat all these relationships as a single class of assets. That is, interests in notable relationship entities will be a separate line item in the balance sheet in the investor’s separate financial statements.
What is a notable relationship entity?
Although AASB 1061 gives an investor the choice to collectively classify its investments in subsidiaries, associates and joint ventures as ‘notable relationship entities’, in practice, the NFP may not know whether its investments are subsidiaries, associates or joint ventures because conducting such an assessment is too time-consuming, difficult and/or judgemental.
AASB 1061 has simplified this assessment process. Basically, a ‘notable relationship entity’ is one in which the investor has the power, at a minimum, to participate in the financial and operating policy decisions of the investee. This occurs when the investor has at least significant influence over the investee.
Note that holding an equity interest is not a prerequisite for an investor to be able to participate in the financial and operating policy decisions of the investee.
Significant influence is usually evidenced in one or more of the following ways:
- Representation on the board of directors or equivalent governing body of the investee
- Participation in policy-making processes, including participation in decisions about distributions of any surpluses
- Material transactions between the two entities
- Interchange of managerial personnel, and
- Provision of essential technical information.
Deciding whether the investor has significant influence over the investee requires judgement. For example:
- Significant influence presumed: Entity holds, directly or indirectly, 20 per cent or more of the voting power of an investee
- Significant influence not presumed: Entity holds, directly or indirectly, less than 20 per cent of the voting power of the investee.
In the above instances, significant influence is presumed/not presumed unless it can be clearly demonstrated otherwise.
Potential voting rights that are currently exercisable or convertible (including those held by other entities) are also considered when assessing whether an entity has significant influence.
What are separate financial statements?
Separate financial statements are:
- The financial statements presented by an investor that accounts for investments in notable relationship entities
- A second set of financial statements that a parent elects to present in addition to consolidated financial statements
- A second set of financial statements that an investor (which is not a parent but has one or more investments in associates or joint ventures) elects to present in addition to its individual financial statements, which have equity accounted its investments in associates and joint ventures.
How are investments measured in separate financial statements?
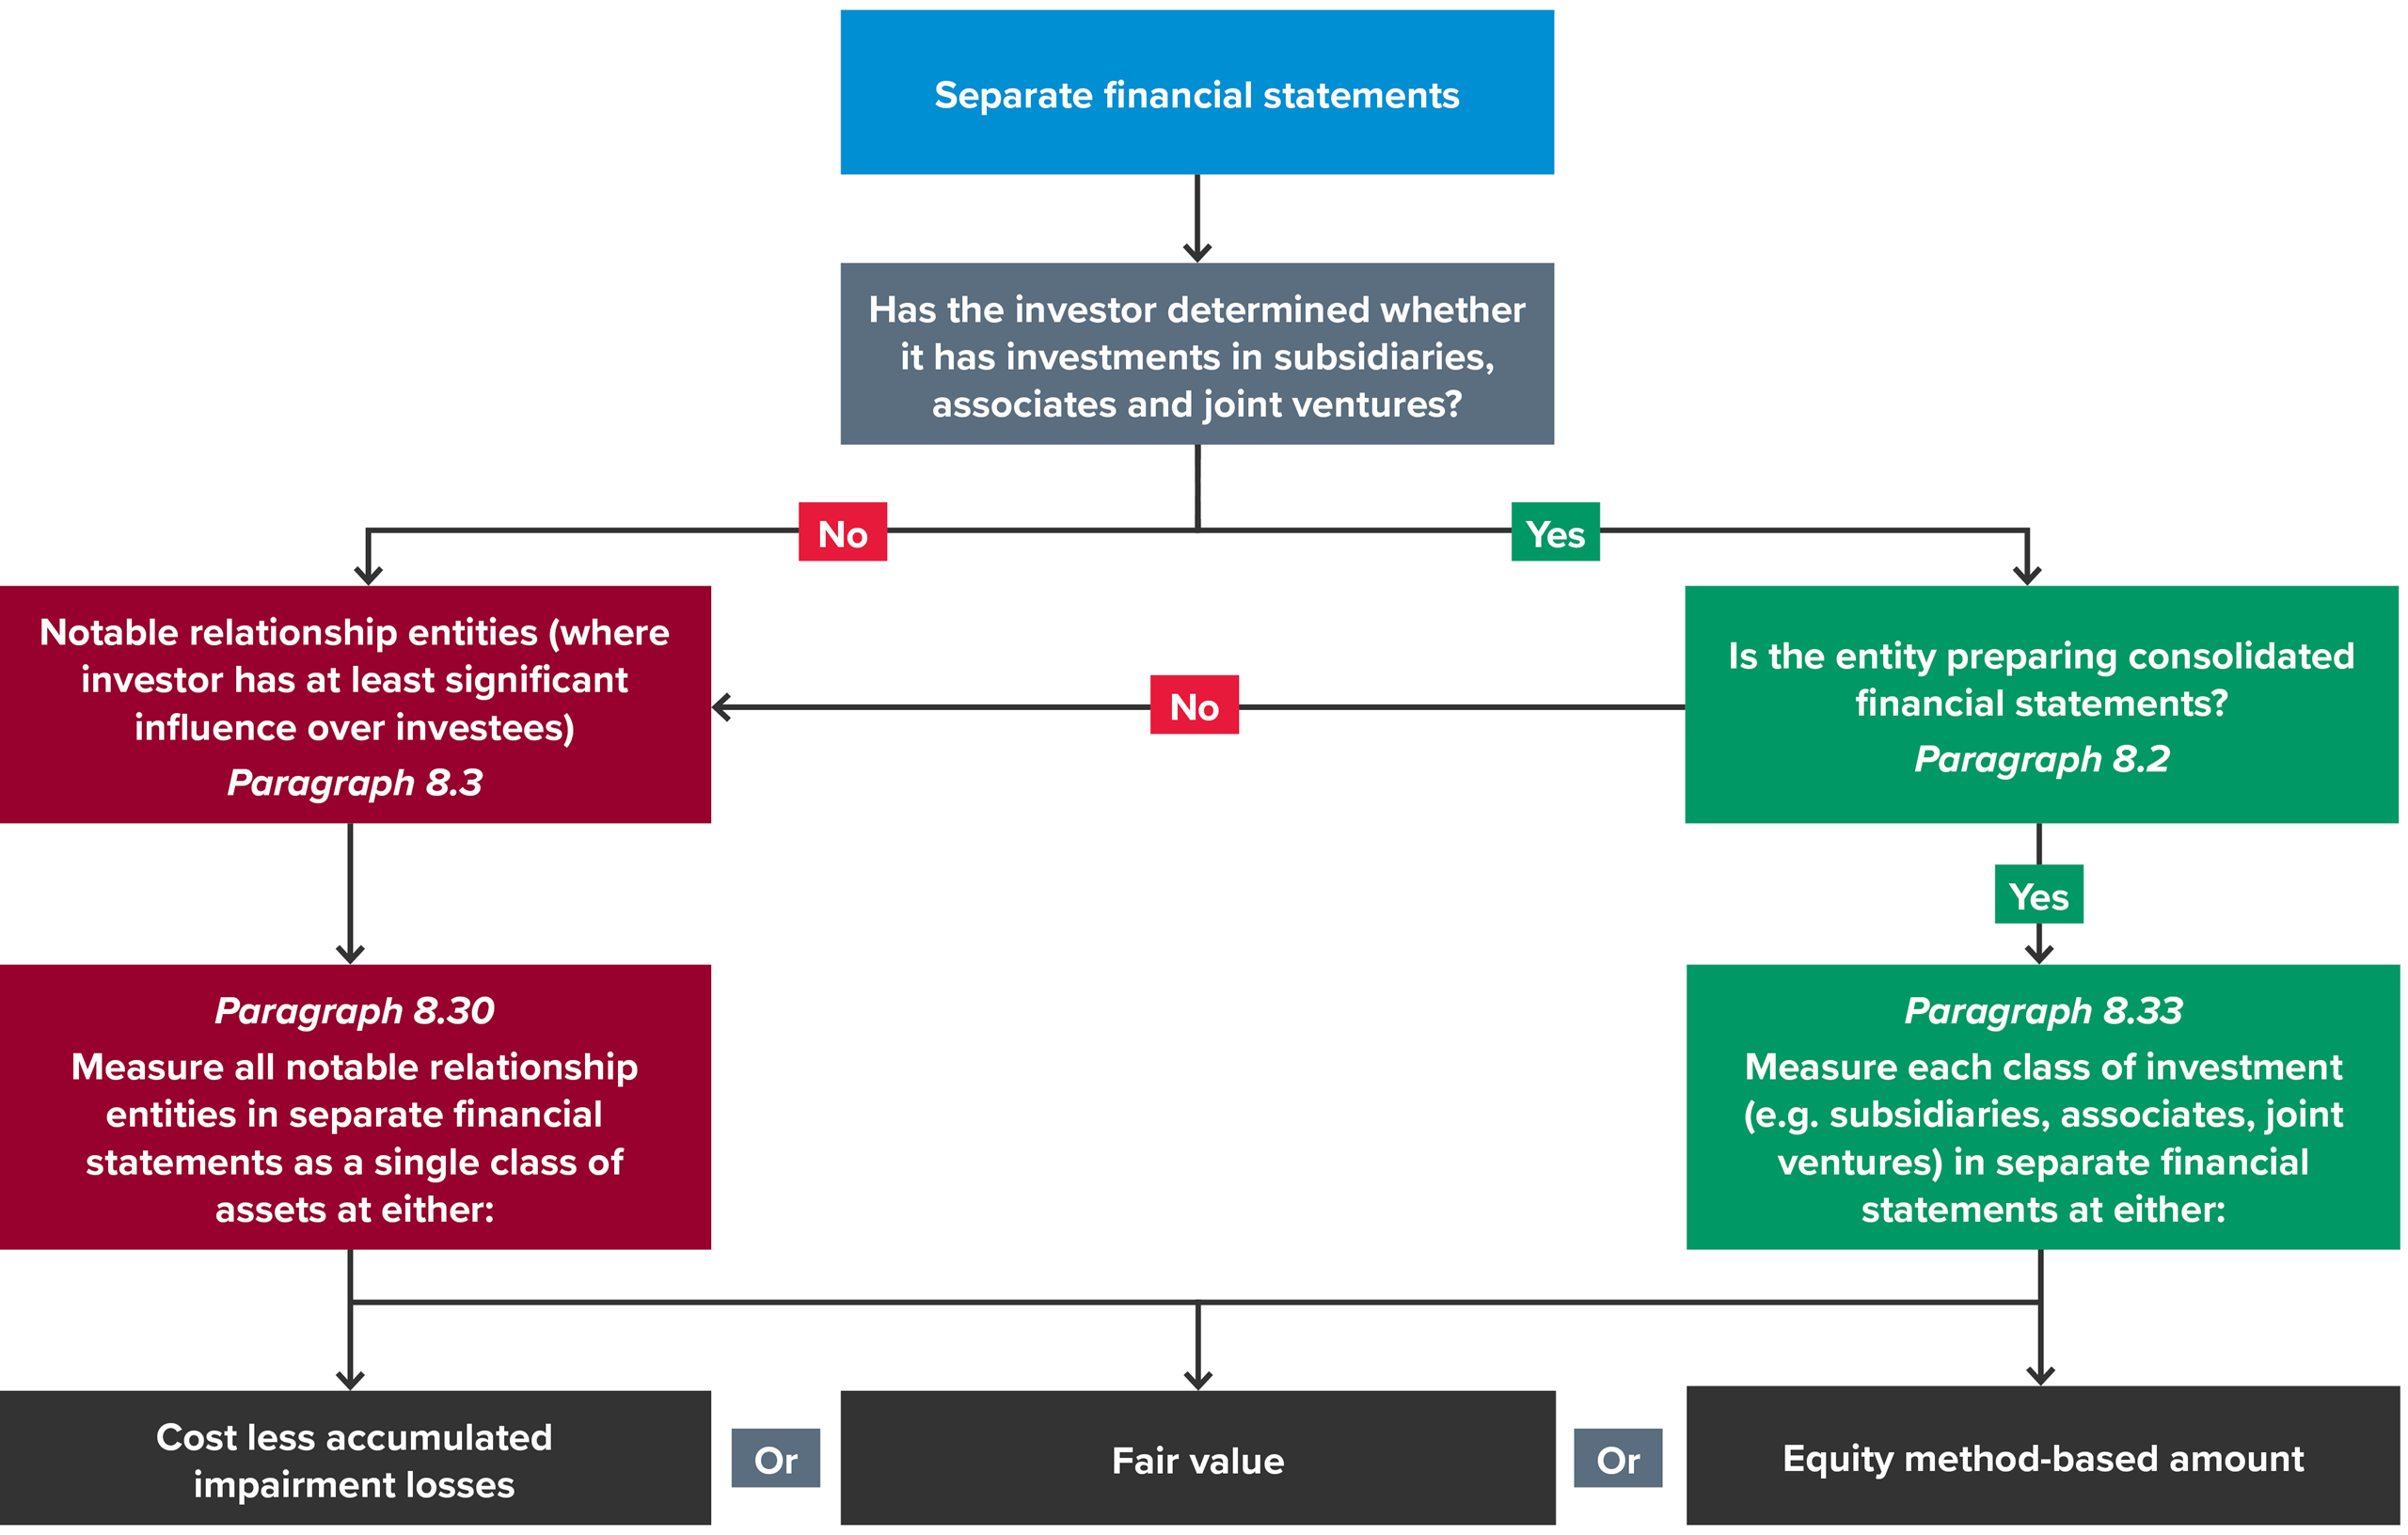
The rules for measuring investments in separate financial statements differ, depending on whether the investor has determined whether it has investments in subsidiaries, associates and joint ventures. This is shown in the diagram below.
Separate financial statements with investments in notable relationship entities
If the investor has not assessed whether it has investments in subsidiaries, associates and joint ventures, and has elected to collectively classify its investments as notable relationship entities, it must choose to measure all investments in notable relationship entities at either:
- Cost, less any accumulated impairment losses (determined by referring to the requirements in Section 10 for identifying and measuring impairment of financial assets measured at cost)
- Fair value, or
- Equity method-based amount (determined by following the equity accounting procedures in paragraph 13.22).
It is important to note that all investments in notable relationship entities are treated as a single class of assets, and the investor must apply the same measurement accounting policy to all such investments, including future notable relationship investments.
Example: Notable relationship entities
Entity A does not assess whether it has investments in subsidiaries, associates and joint ventures.
Entity A has investments in Entity X, Entity Y and Entity Z. It collectively classifies all three investments as notable relationship entities because it has at least significant influence in all of them.
In its separate financial statements, being the entity’s only financial statements, Entity A can measure all investments in notable relationship entities at cost, all at fair value, or all using the equity method-based amount.
Separate financial statements in addition to consolidated/equity-accounted financial statements
As noted above, a parent entity can choose to present separate financial statements as a second set of financial statements in addition to consolidated financial statements. An investor with one or more investments in associates or joint ventures can make a similar choice.
The parent or investor can choose to measure these investments in subsidiaries, associates and joint ventures using the same three measurement options available for notable relationship entities. However, each class of investment can use a different measurement basis.
Example: Investments in subsidiaries, associates and joint ventures
Entity B has assessed that it has investments in subsidiaries, associates and joint ventures and has elected to prepare consolidated financial statements.
Entity B wishes to present separate financial statements in addition to its consolidated financial statements.
Entity B can choose to measure each class of investment using one of the three methods noted above. For example, it can choose to measure subsidiaries at cost, associates at fair value, and joint ventures using the equity method-based amount.
However, Entity B cannot choose to measure some subsidiaries at cost and some using another measurement basis.
Fair value measurement
Where fair value is selected as the measurement basis, changes in fair value are recognised in profit or loss, unless the investor makes an irrevocable election to present fair value changes in OCI (FVTOCI). However, the criterion for making this irrevocable election differs as follows:
Type of investment | When to make an irrevocable election for FVTOCI | Implication |
Investment in notable relationship entities | On the initial recording of the first asset in the class of assets called ‘investments in notable relationship entities’ | An election cannot be made after the first investment in a notable relationship entity has been recognised |
Investments in subsidiaries, associates and joint ventures | On the initial recording of its first investment in each class of asset. | An election can be made the first time that a subsidiary, associate or joint venture is recognised. |
Entities transitioning to Tier 3 for the first time can make the irrevocable election to present these investments at FVTOCI based on facts and circumstances that exist on the date of transition, as if the date of transition were the date of initial recording of the first asset in the class.
Disclosures in separate financial statements
For all entities preparing separate financial statements, the following additional disclosures are required:
- The fact that the financial statements are separate financial statements
- A description of the method(s) used to account for its:
- Investments in notable relationship entities (all would have the same measurement basis), or
- Investments in subsidiaries, associates and joint ventures (each could have a different measurement basis).
In addition to the related party disclosures required by Section 27, an entity must disclose for each notable relationship entity:
- The name of the notable relationship entity
- A description of the notable relationship entity’s primary purpose and an indication of the nature of its operations
- A description of the notable relationship entity’s relationship with the reporting entity (for example, that the entities operate a partnership, that the reporting entity is able to appoint the key management personnel of the notable relationship entity, or that the entity controls the notable relationship entity)
- Whether the notable relationship entity prepares audited or reviewed financial statements.
Accounting policies, errors and estimates (section 9)
Key points to note regarding changes in accounting policies, estimates and errors:
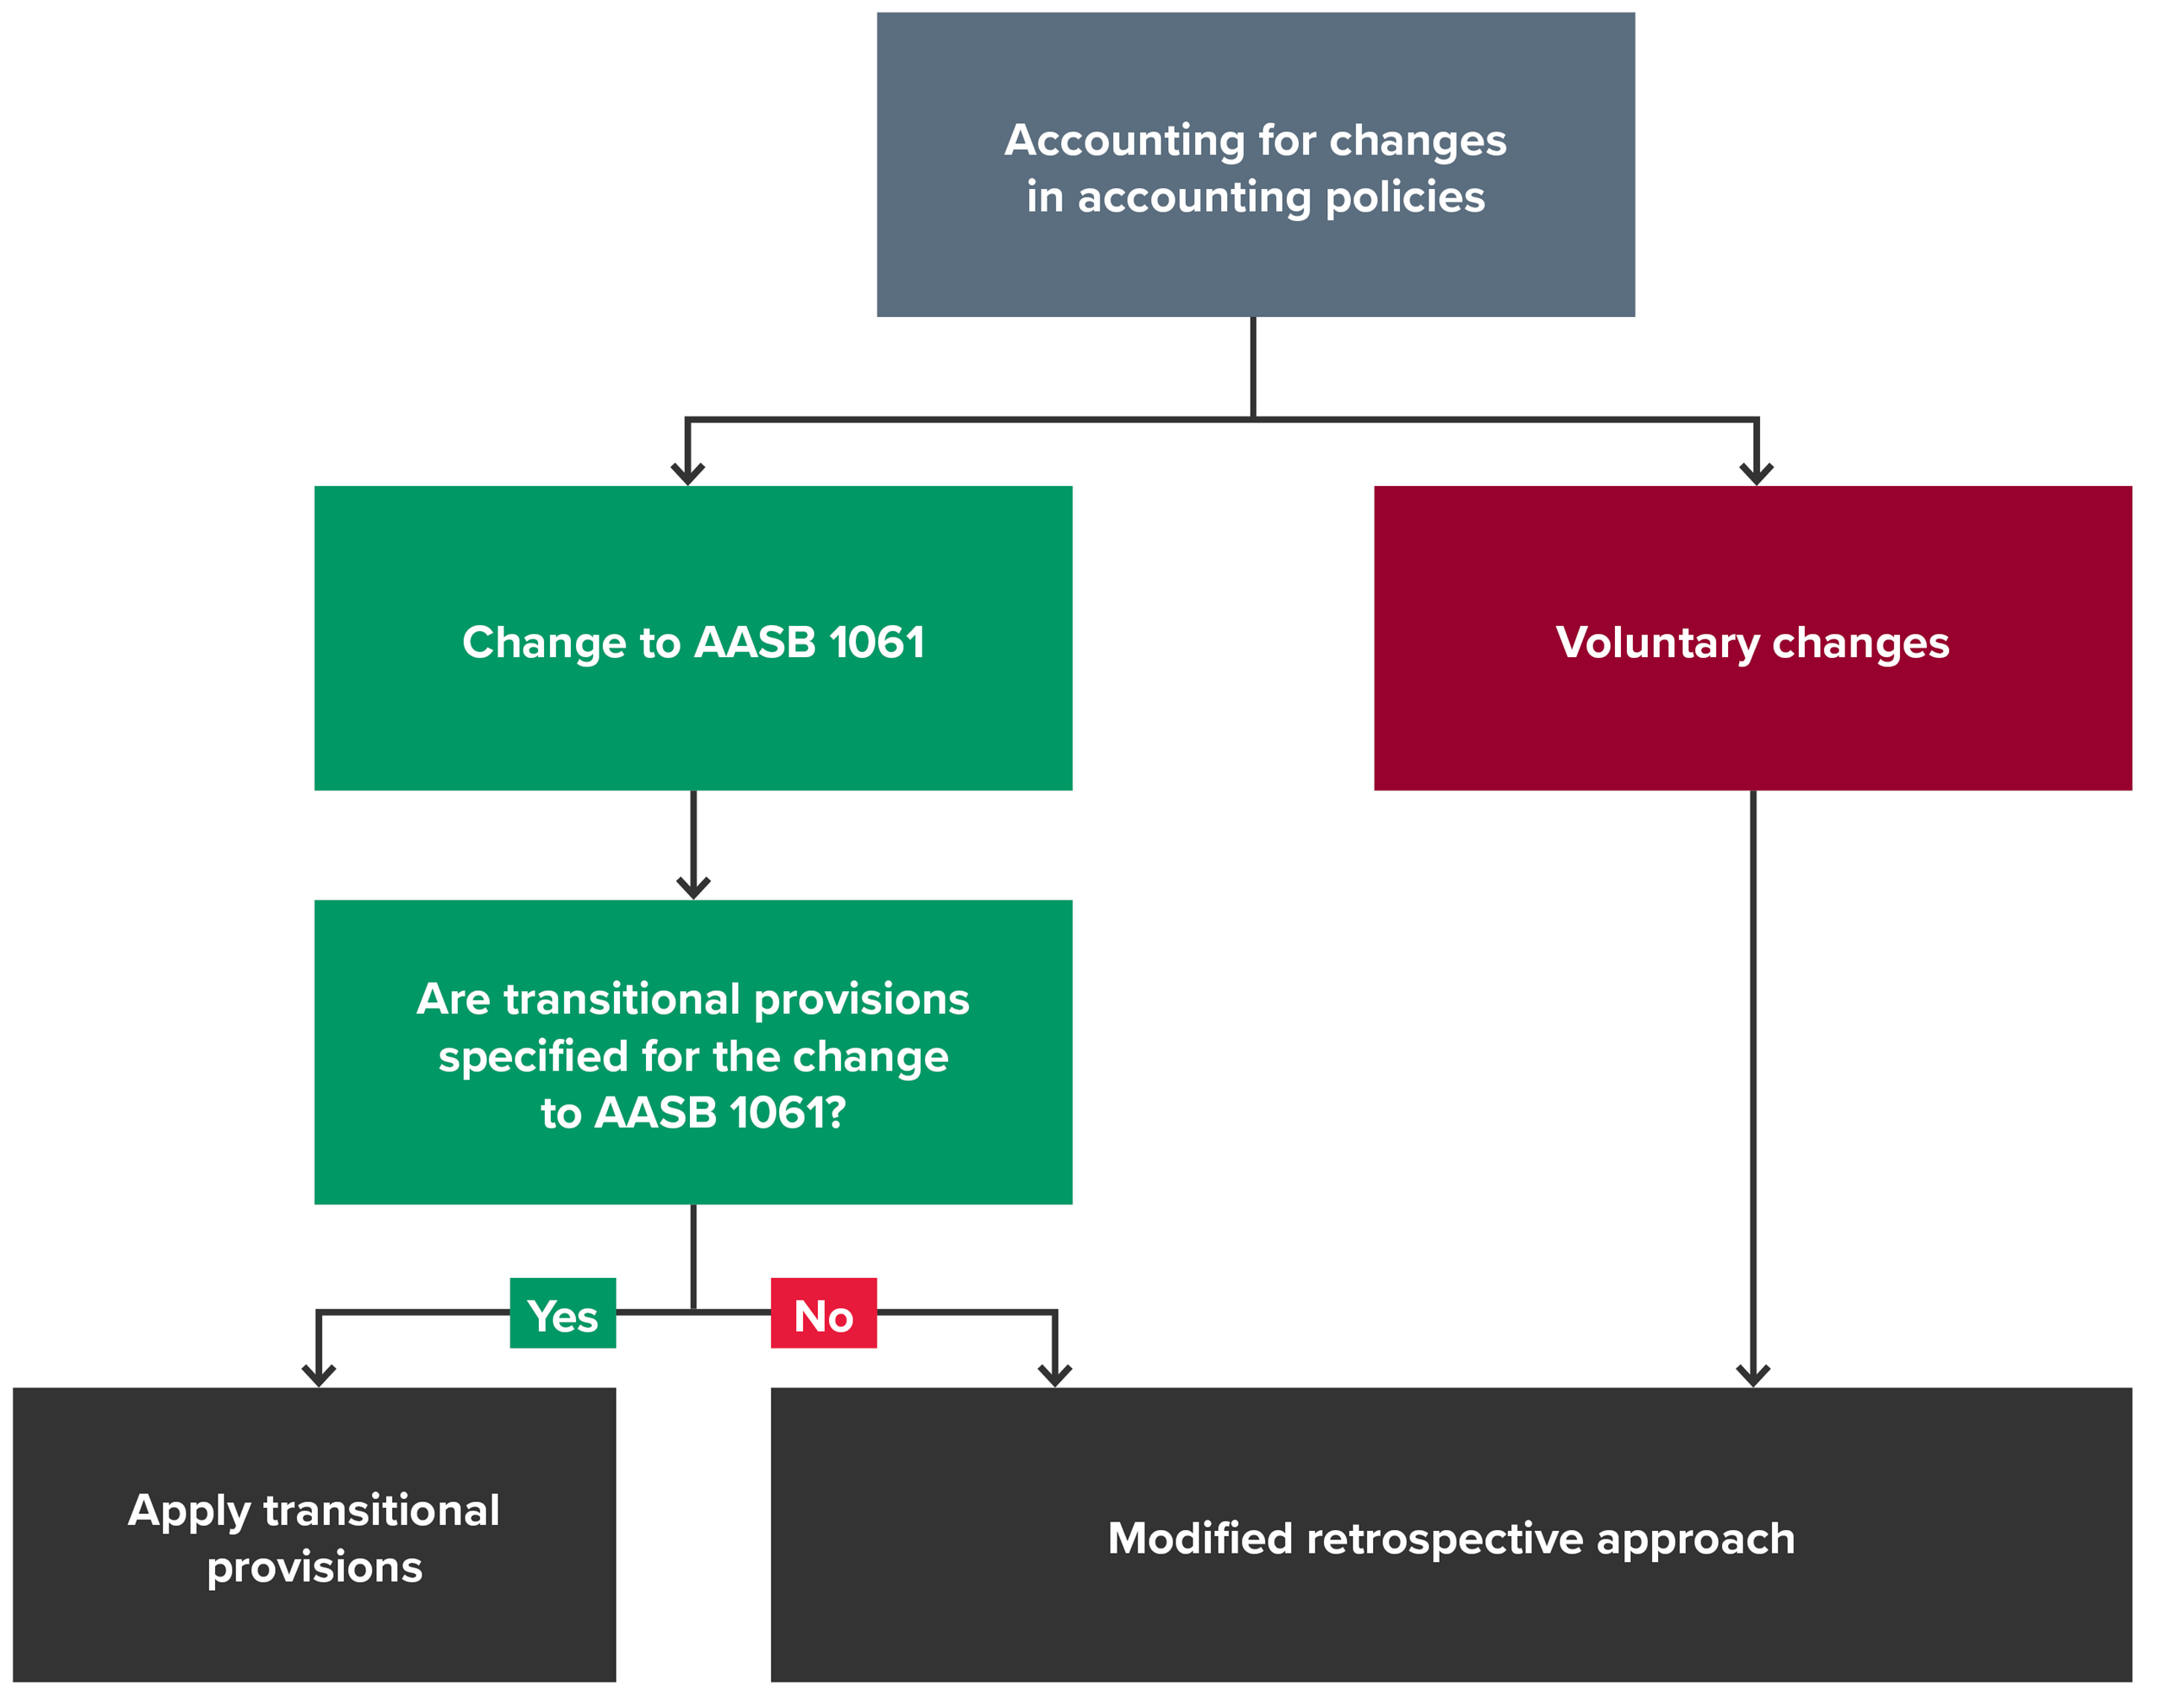
- Changes in accounting policies required by amendments to AASB 1061 are accounted for in accordance with the transitional requirements associated with the amendments, and if there are none, then using by applying the modified retrospective approach (with no restatement of comparatives but the effects of retrospective restatement recognised at the beginning of the current period).
- Voluntary changes in accounting policies are accounted for by applying the modified retrospective approach.
- Changes in estimates are recognised prospectively from the date that the change occurs.
- Material prior period errors are accounted for by applying the full retrospective approach (with restatement of comparatives).
Which accounting policies to apply?
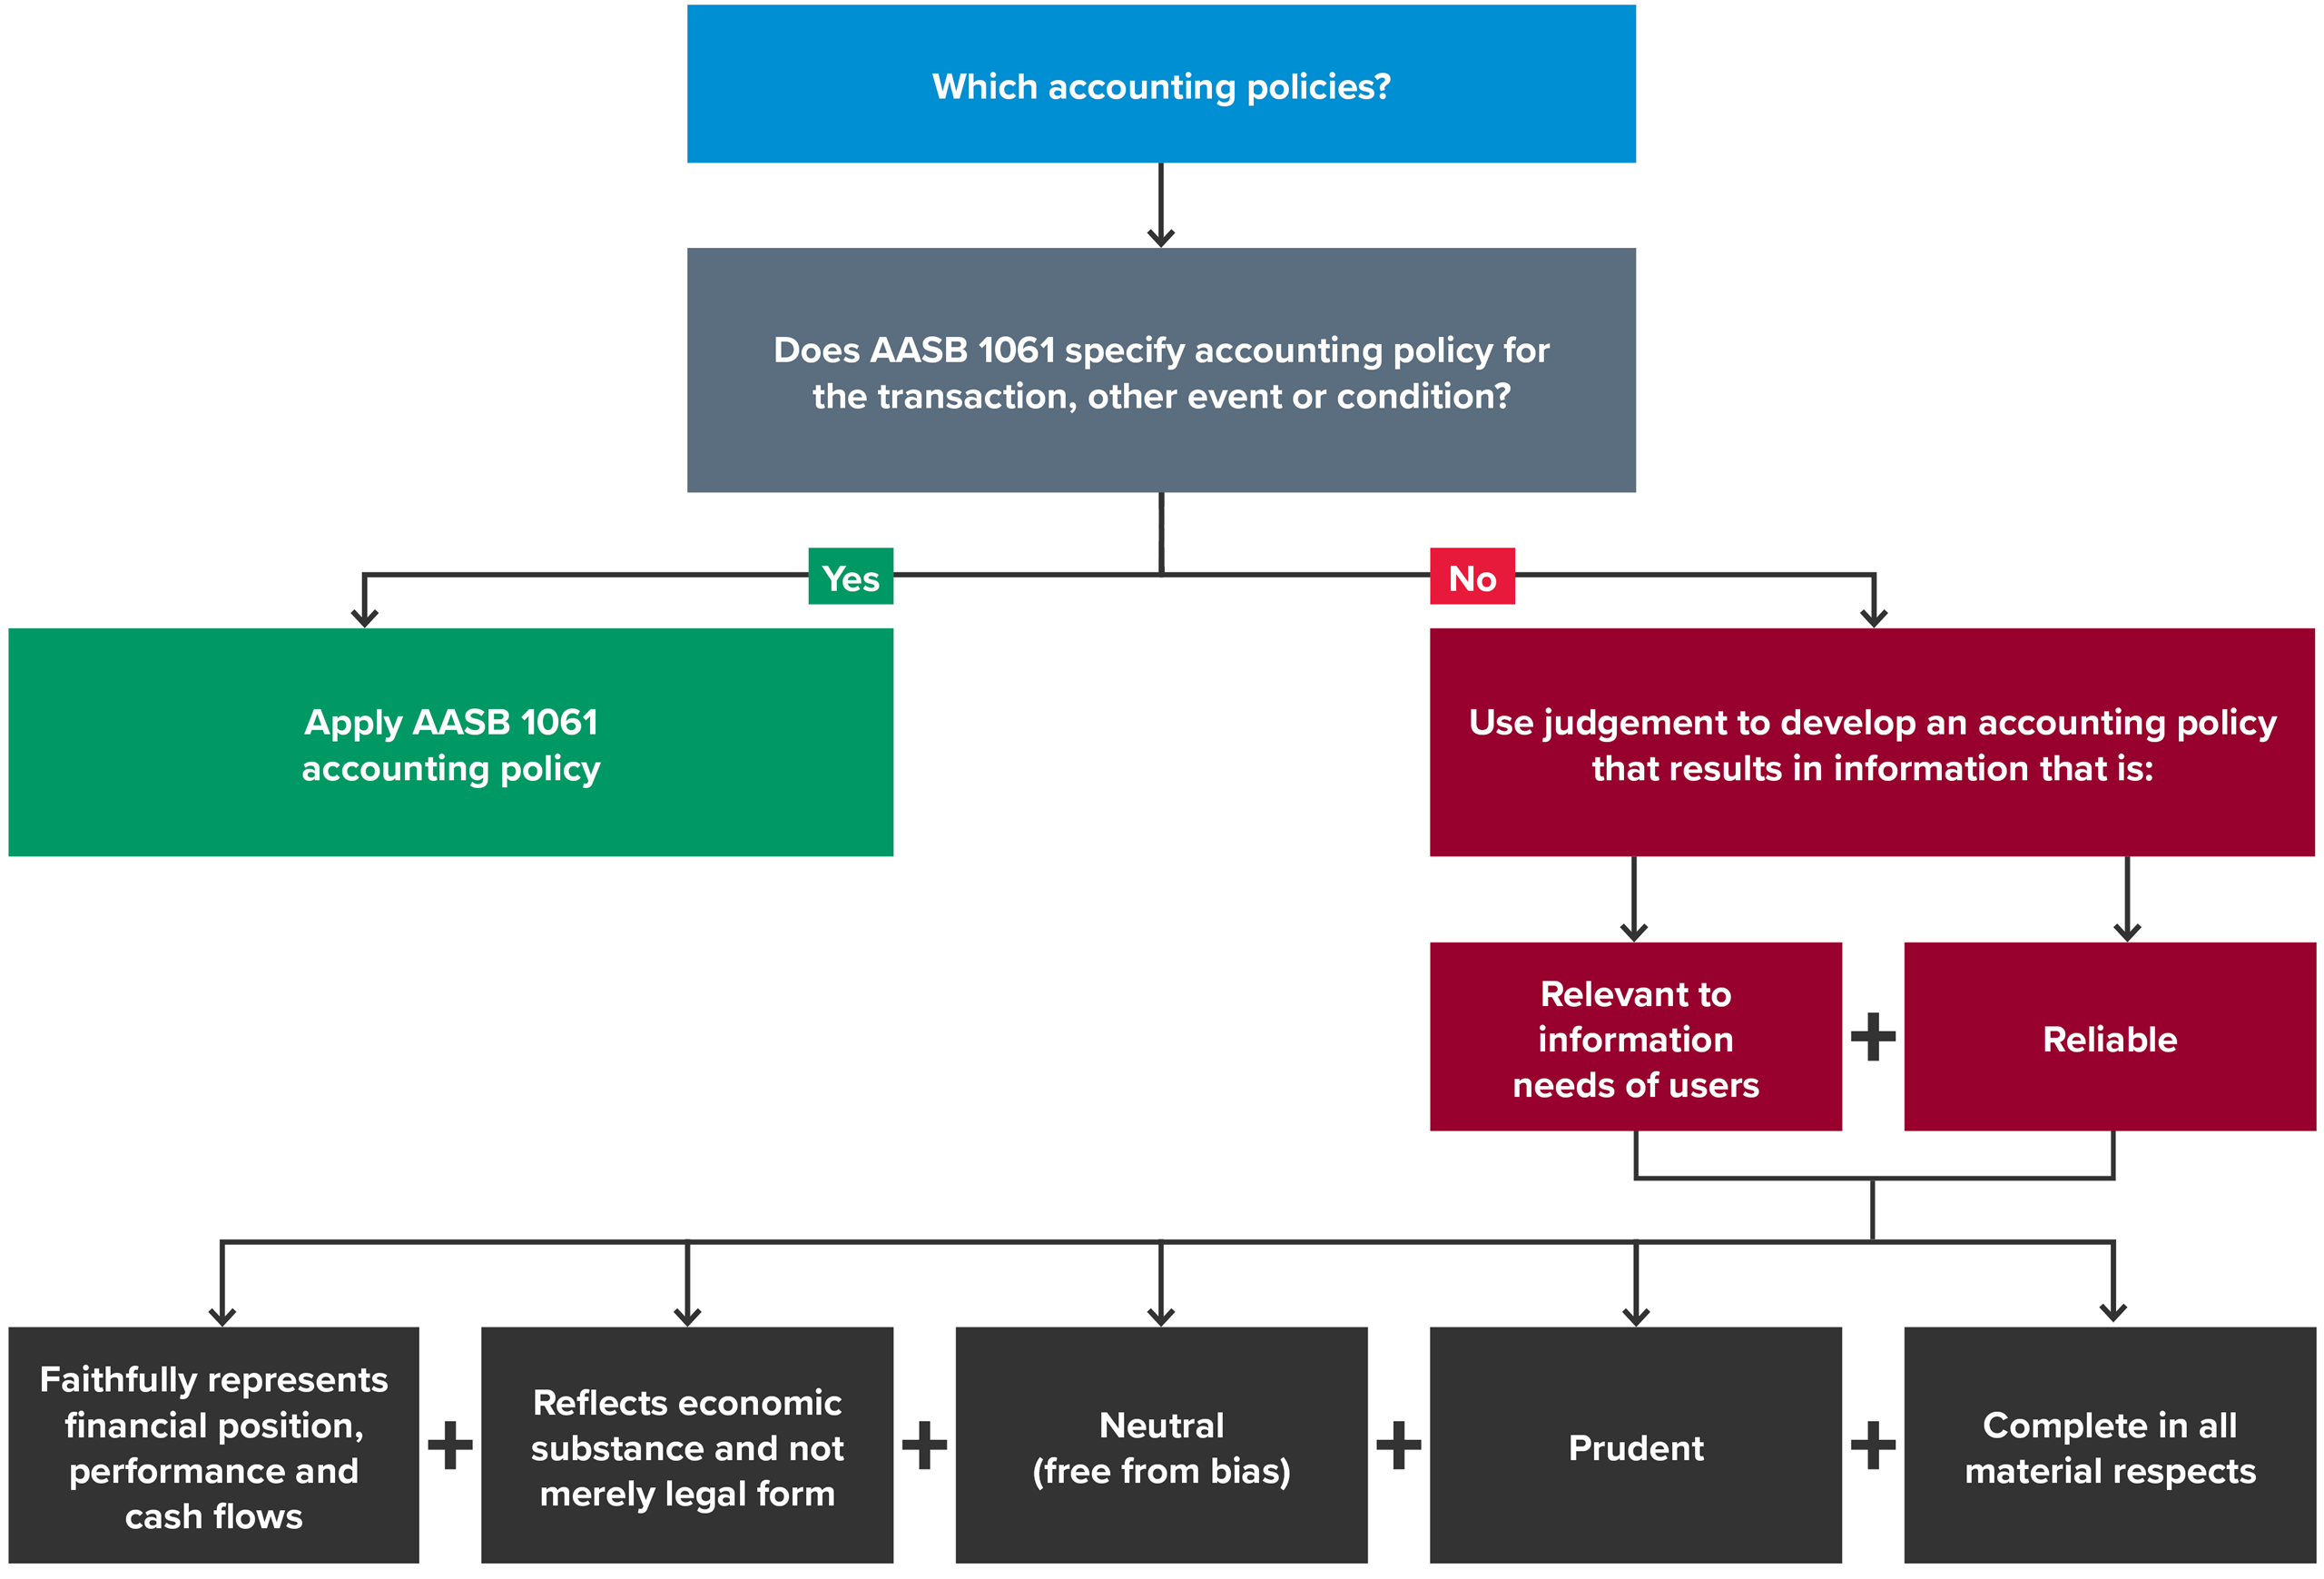
If AASB 1061 contains a specific requirement regarding the recording and measurement of a particular type of transaction, other event or condition, Tier 3 NFPs must apply the stated accounting policy.
Tier 3 NFPs need not apply the accounting policies set out in AASB 1061 if the effect is immaterial.
If AASB 1061 does not set out a specific accounting policy, Tier 3 NFPs must use judgement to develop an accounting policy that results in information that is relevant to the information needs of users of financial statements and reliable. Information is reliable when it faithfully represents the financial position, financial performance and cash flows of the entity, reflects the economic substance of transactions, other events and conditions (not merely their legal form), is neutral (free from bias), prudent and complete in all material respects.
Hierarchy when making judgements to develop accounting policies
In making judgement to develop accounting policies where AASB 1061 does not set out specific accounting policies, management must consider the following sources in descending order:
| Requirements and guidance in AASB 1061 dealing with similar and related issues |
↓ |
| Definitions, recognition criteria and measurement concepts for assets, liabilities, income and expenses in the Conceptual Framework. |
Management may also consider the requirements and guidance in other Australian Accounting Standards that address similar or related issues, to the extent that such requirements and guidance do not conflict with this Standard.
Consistency of accounting policies
Generally, consistent accounting policies should be applied for similar transactions, other events and conditions.
This applies unless AASB 1061 allows or requires categorisation of items such that different policies may be appropriate, for example, applying a subsequent measurement cost model to certain classes of property, plant and equipment and a fair value model to others. In such cases, the entity selects the appropriate accounting policy and applies it consistently to each category.
When can an entity change accounting policies?
Tier 3 NFPs can only change an accounting policy if the change:
- Is required by AASB 1061, or
- Results in the financial statements providing reliable and more relevant information about the effects of transactions, other events or conditions on the entity’s financial position, financial performance or cash flows (voluntary change).
What is considered a change in accounting policy?
Where AASB 1061 allows a choice of accounting treatment, including measurement basis, changing the choice is generally considered a change in accounting policy. For example, changing from measuring a class of property, plant and equipment using a cost model to a fair value model is a change in accounting policy.
What is not considered a change in accounting policy?
The following are not considered changes in an accounting policy:
- A change between presenting total comprehensive income using a single statement approach to a two-statement approach (refer to paragraph 4.4)
- A change between presenting a statement of income and retained earnings to presenting both a statement of financial performance and a statement of changes in equity (refer to paragraph 5.5)
- For an asset that AASB 1061 requires or permits a fair value measurement model:
- A change to applying the cost model when a reliable measure of fair value is no longer available
- Reverting to applying the revaluation model when a reliable measure of fair value once again becomes available.
How to account for a change in accounting policy?
Tier 3 NFPs will look to any specific transitional provisions in AASB 1061 to determine whether retrospective restatements are required, or whether the change applies going forward.
If no transitional provisions are specified, the change is accounted for retrospectively, using the modified retrospective approach.
Assuming the requirements for voluntary changes in accounting policies are met, the change is accounted for retrospectively, using the modified retrospective approach.
What is the modified respective approach?
The entity applies the following steps when applying the modified retrospective approach:
- Record the cumulative effect of the new accounting policy at the beginning of the current reporting period, as if the new accounting policy had always been applied
- Don’t restate information presented in prior periods
- Adjust the opening balance of each affected asset and liability for the cumulative effect of applying the new accounting policy at the beginning of the current period
- Make a corresponding adjustment to the opening balance of each affected component of equity (e.g. retained earnings) at the beginning of the current period
The effects of the change in accounting policy relating to prior periods presented are not included in profit or loss of the current reporting period.
What if it is impracticable to determine the cumulative effect of applying a new policy retrospectively?
If it is impracticable to determine the cumulative effect of applying a new accounting policy retrospectively to all prior periods, the Tier 3 NFP must determine the retrospective cumulative effect from the start of the earliest date practicable. Any cumulative adjustment to assets, liabilities and items of equity arising before this date are disregarded.
Changes from cost to fair value model are accounted for prospectively
If a Tier 3 NFP decides to switch from a cost to a revaluation model for property, plant and equipment or intangible assets, this is accounted for as a revaluation in accordance with section 15 or 16 of AASB 1061and accounted for prospectively, instead of by applying the modified retrospective approach.
Accounting policy disclosures
The following disclosures are required when either there is a change to AASB 1061 or a voluntary change in accounting policy, and the change affects the opening balances of assets, liabilities or equity for the current period, or other amounts recorded for the current period:
- Nature of the change in accounting policy
- Amounts of the adjustments to the opening balances for the current period, to the extent practicable (this will affect assets, liabilities, retained earnings and equity)
- For all other effects on the assets, liabilities, income and expenses for the current period, the amount of the adjustment for each financial statement line item affected.
When a modified retrospective approach is applied to a change in an accounting policy, the entity’s material accounting policy note must disclose that comparative information presented for prior periods was not adjusted.
In addition to the above disclosures, when a Tier 3 NFP makes a voluntary change, it must disclose the reasons why applying the new accounting policy provides reliable and relevant information.
These need not be repeated in financial statements of subsequent periods.
Accounting estimates
Some items in financial statements are subject to measurement uncertainty. This occurs where their amounts cannot be observed directly and must instead be estimated using judgements or assumptions about such matters as: the fair value of infrequently sold assets; amounts recoverable from overdue receivables or old inventory; and the remaining useful lives of items of property, plant and equipment.
How to account for a change in accounting estimate?
A Tier 3 NFP may need to change an accounting estimate if circumstances change on which the estimate was based, new information becomes available, or new developments or additional experience require the estimate to be revisited.
Changes in estimates are accounted for prospectively from the date of the change in estimate by including it in profit or loss in:
- The period of the change, if the change affects that period only, or
- The period of the change and future periods, if the change affects both.
There is no restatement of prior period financial statements.
If the revised estimate results in changes to the amounts of assets, liabilities, or equity, the Tier 3 NFP will record the difference by adjusting the carrying amount of the related asset, liability, or equity item in the period of the change.
Change in estimate disclosures
A Tier 3 NFP must disclose the following information about changes in estimates:
- The nature of the change (i.e. provide a narrative description)
- The effect of the change on assets, liabilities, income and expenses for the current period.
Corrections of prior period errors
Prior period errors are omissions from, and misstatements in, an entity’s financial statements for one or more prior periods arising from a failure to use, or misuse of, reliable information that:
- Was available when financial statements for those periods were authorised for issue, and
- Could reasonably be expected to have been obtained and taken into account in the preparation and presentation of those financial statements.
This includes the effects of mathematical mistakes, mistakes in applying accounting policies, oversights or misinterpretations of facts, and fraud.
Potential errors identified during the reporting period must be corrected before the financial statements are authorised for issue.
How to account for a material prior period error?
If a Tier 3 NFP discovers a material prior period error, it must correct the error (to the extent practicable) in its next set of financial statements. The error is corrected retrospectively by:
- Restating the comparative amounts for the prior period presented in which the error occurred, or
- If the error occurred before the earliest prior period presented, restating the opening balances of assets, liabilities and equity for the earliest prior period presented.
When it is impracticable to determine the effects of an error on comparative information for one or more prior periods presented, the entity must restate the opening balances of assets, liabilities and equity for the earliest period for which retrospective restatement is practicable (which might be the current period).
Prior period error disclosures
A Tier 3 NFP must disclose the following about material prior period errors:
- A description of the error
- For each prior period presented (to the extent practicable), the amount of the correction for each financial statement line item affected
- To the extent practicable, the amount of the correction at the beginning of the earliest prior period presented
- An explanation if it is not practicable to determine the error amounts for prior periods and at the beginning of the earliest prior period presented.
These disclosures need not be repeated in financial statements of subsequent periods.
Other considerations
Points for entities to consider regarding the Tier 3 reporting framework:
- AASB 1061 uses simplified, but sometimes similar, wording that may nevertheless result in potential recognition and measurement differences compared to Tier 1/Tier 2 general purpose financial statements
- If/how these consolidation simplifications will affect the thresholds for reporting once legislators decide who can apply AAS B 1061.
Where to from here?
As noted earlier, until the legislators decide on the criteria for Tier 3 GPFS, at this stage, we recommend private sector NFPs to carefully consider AASB 1061 adoption plans and consult. With the transition date (1 July 2029) still three years away, and no restatement of comparatives required, entities will have time to prepare. However, despite simplified requirements, adoption efforts should not be underestimated and left too late prior to the mandatory effective date. In the meantime, future editions of Corporate Reporting Insights will provide further insights into some of the areas where recording and measurement could change for Tier 3 entities.
We are here to help
Whilst AASB 1061 simplifies the requirements for eligible entities, navigating the financial reporting framework for NFPs is currently a complex exercise because regulators have not yet addressed the existence of Tier 3. In addition, the requirements for general purpose financial statements (GPFS), which kick in in 2029 will be challenging for many NFPs currently preparing special purpose financial statements (SPFS), and the transition effort required to move from SPFS to a form of GPFS should not be under-estimated. Please contact our IFRS & Corporate Reporting team if you need help deciphering the new standards.